Wondering how much it takes to build a loan platform without blowing your budget?
Lending software development in South Africa can cost ZAR 40K to ZAR 1M, depending on the features, platform type, integrations, and security needs.
A basic loan management system costs less than a full digital lending platform with automated credit scoring, loan approvals, payment processing, and borrower dashboards.
This guide breaks down the costs, key features, local regulations, technology choices, and practical ways to save money.
- Most lending software projects in South Africa fall between ZAR 40K and ZAR 1M, depending on scope, integrations, and security.
- Loan origination, LMS, digital lending, P2P, microfinance, mobile, and BNPL platforms each carry different feature sets and price bands.
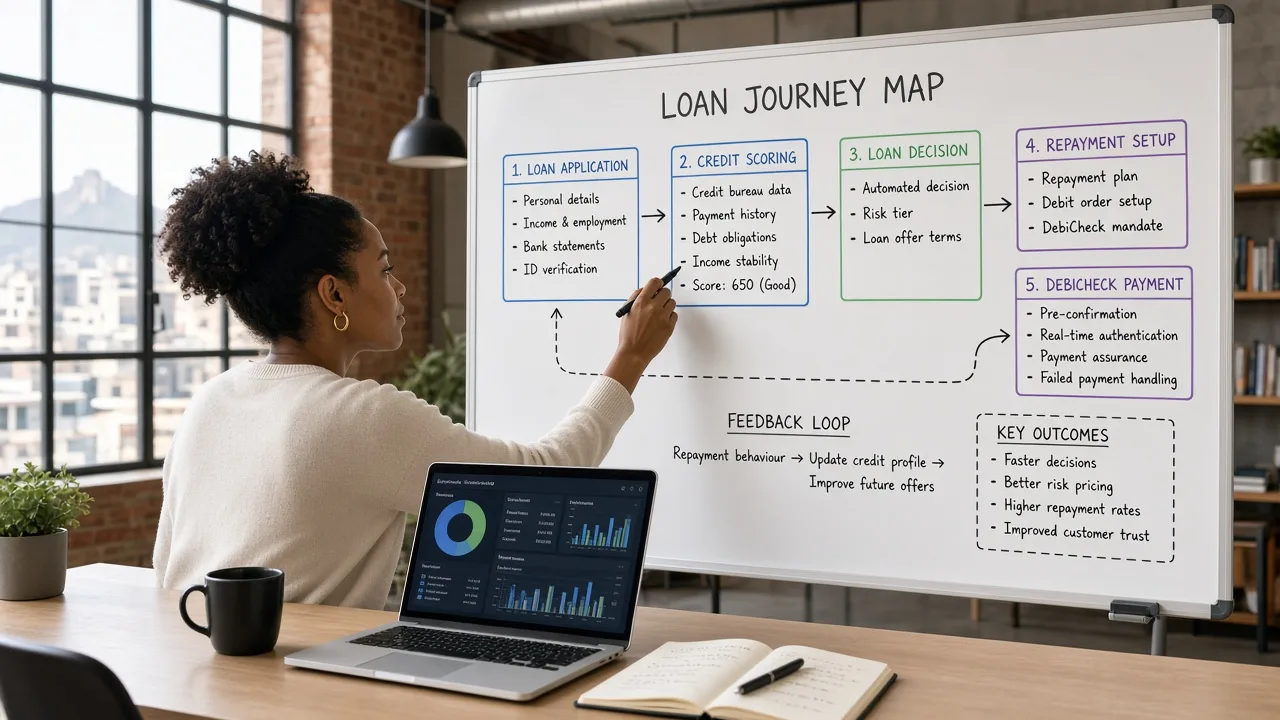
- Nine core modules—from origination and credit scoring to DebiCheck payments—drive most of the development budget.
- NCA, POPIA, FICA, DebiCheck, and credit bureau APIs shape compliance work and integration costs from day one.
- An MVP, early integration planning, and the right development partner helped many teams control spend without cutting corners.
What Is Lending Software, and What Are the Benefits of Lending Software Development?
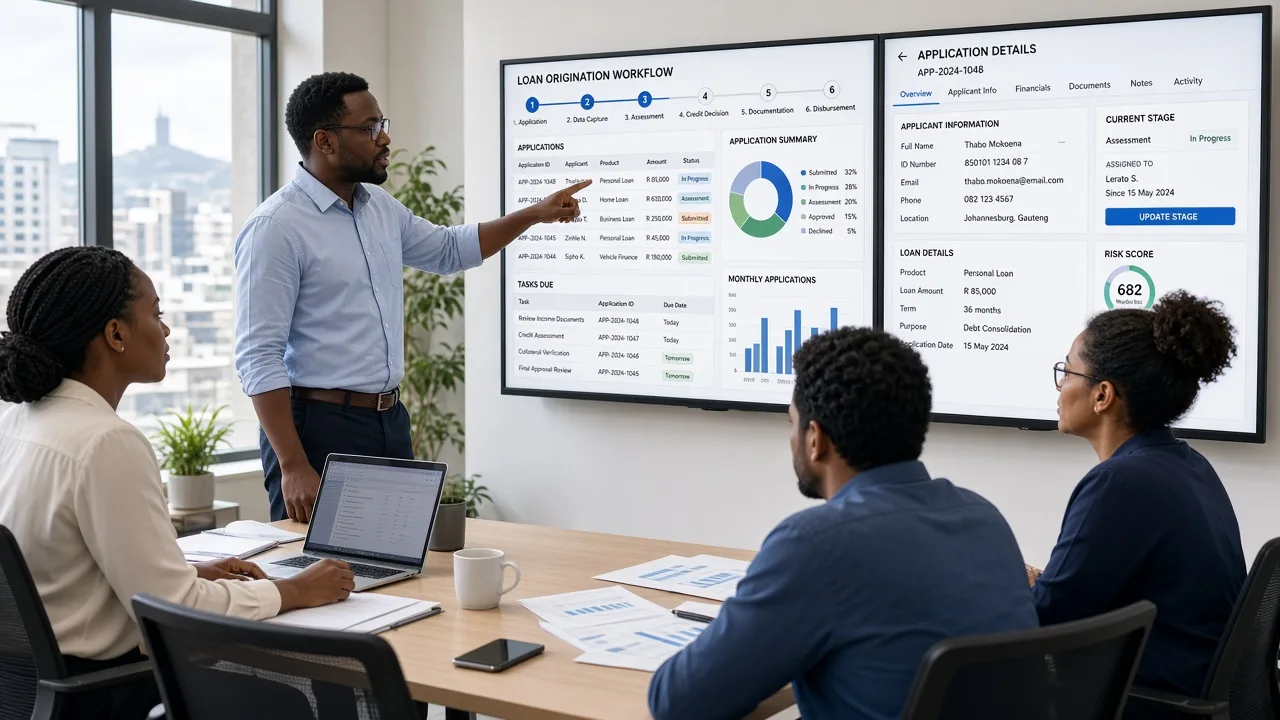
Lending software is a digital system that helps lenders manage the full loan process, from online applications and credit checks to loan approvals, fund disbursement, repayments, and borrower records.
Key Benefits of Lending Software Development
Faster loan processing
Automated loan applications, credit checks, approval steps, and fund disbursement cut the time between application and payout.
Better borrower experience
Customers apply online, upload documents, track applications, and check repayment schedules without calling the office for every update.
Fewer manual errors
Digital records reduce paperwork and mistakes in loan calculations, interest rates, and payment histories.
Smarter credit decisions
Credit scoring, borrower data, and risk checks support more consistent lending decisions across your team.
Easier loan management
Teams track outstanding balances, instalments, overdue payments, and collections activity from one dashboard.
Room to grow
With lending software development in South Africa, lenders can build systems that support local payment methods, credit bureau checks, and changing business needs.
What Is the Cost of Lending Software Development in South Africa?
Lending software development costs in South Africa range from ZAR 40K to ZAR 1M, based on project size, features, integrations, and complexity.
| Package | Estimated Cost | Estimated Timeline | Best For |
|---|---|---|---|
| Starter | ZAR 40K–ZAR 100K | 4–8 weeks | Small lenders, internal tools, and MVP loan systems |
| Growth | ZAR 100K–ZAR 400K | 8–16 weeks | Growing lenders needing custom platforms, API links, and workflow automation |
| Enterprise | ZAR 400K–ZAR 1M | 4–8 months | Large lenders needing advanced security, multiple integrations, and scalable systems |
What Type of Lending Software Do You Need?
The right lending software depends on your loan model, business size, users, and the features your team needs.
| Lending Software Type | Description | Estimated Cost (ZAR) |
|---|---|---|
| Loan Origination Software (LOS) | Manages loan applications, document checks, credit scoring, and approval workflows. | ZAR 100K–ZAR 400K |
| Loan Management Software (LMS) | Tracks active loans, interest, repayment schedules, balances, and overdue payments. | ZAR 80K–ZAR 350K |
| Digital Lending Platform | Lets borrowers apply online, get decisions, and manage loans through one platform. | ZAR 200K–ZAR 700K |
| P2P Lending Software | Connects borrowers and lenders, with tools for loan listings, funding, and repayments. | ZAR 250K–ZAR 800K |
| Microfinance Lending Software | Supports small loans, group lending, field agents, and frequent repayments. | ZAR 100K–ZAR 400K |
| Mobile Loan App | Allows users to apply for loans, check status, and make payments on their phones. | ZAR 150K–ZAR 500K |
| Buy Now, Pay Later (BNPL) Software | Splits purchases into instalments and tracks payments, limits, and missed dues. | ZAR 200K–ZAR 600K |
Important Lending Software Features That Affect Development Pricing
The features you choose shape your platform’s price, from basic loan tracking to advanced credit checks and payment automation.
1. Loan Application and Origination
Borrowers apply online, upload documents, and track loan requests. Automated forms and approval steps reduce manual work.
Cost: ZAR 15K–ZAR 60K
2. Borrower and User Management
Stores borrower profiles, contact details, income records, loan history, and user roles. Admins manage customers from one dashboard.
Cost: ZAR 10K–ZAR 40K
3. Credit Scoring and Risk Assessment
Checks credit history, income, and repayment ability to help lenders assess risk. Credit bureau API links can add to the cost.
Cost: ZAR 20K–ZAR 80K
4. Loan Approval and Underwriting
Automates eligibility checks, loan rules, approval steps, and decision records. More complex lending rules need more development time.
Cost: ZAR 15K–ZAR 60K
5. Loan Repayment and Servicing
Tracks instalments, interest, outstanding balances, due dates, and late payments. Automated repayment schedules make daily loan management easier.
Cost: ZAR 15K–ZAR 55K
6. Payment Gateway and Debit Order Integration
Connects the platform to payment providers, EFT services, and debit order systems such as DebiCheck. Provider fees may apply separately.
Cost: ZAR 15K–ZAR 50K
7. Notifications and Alerts
Sends SMS, email, or app alerts for approvals, payment reminders, due dates, and overdue instalments.
Cost: ZAR 5K–ZAR 20K
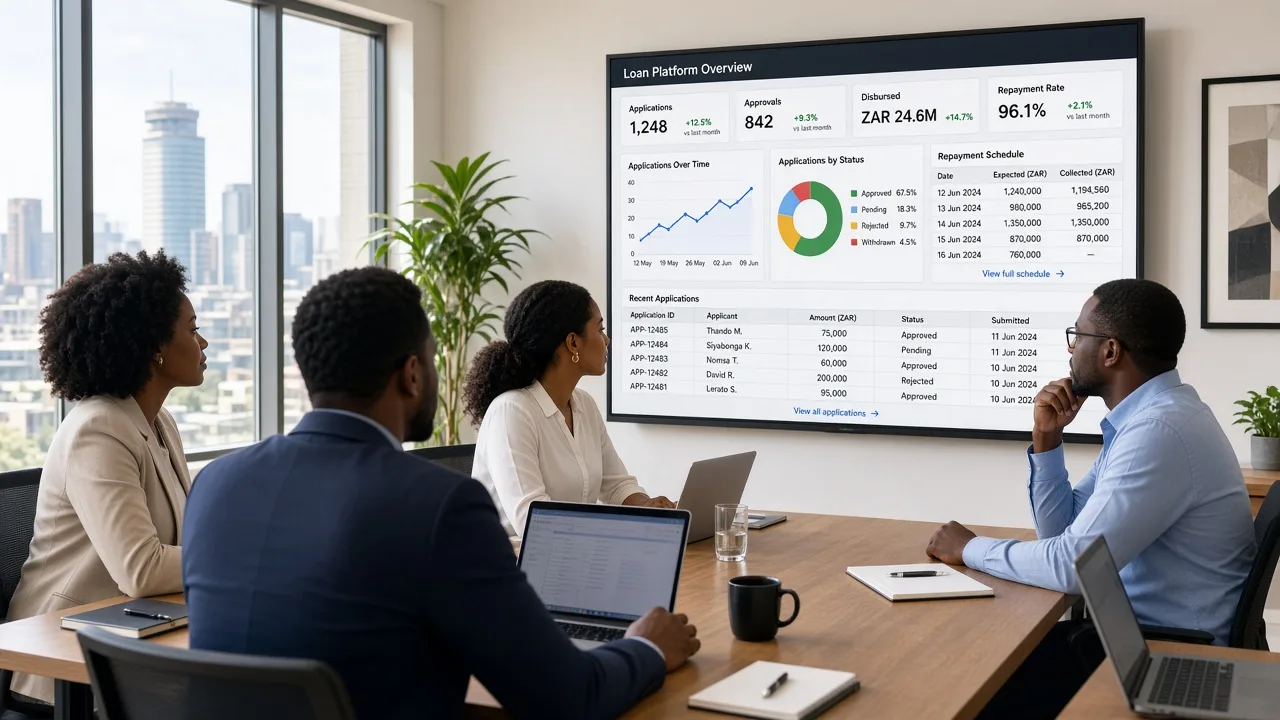
8. Reports and Analytics Dashboard
Shows loan performance, repayment rates, overdue accounts, and revenue. Custom reports help lenders make better business decisions.
Cost: ZAR 10K–ZAR 35K
9. Security and Access Control
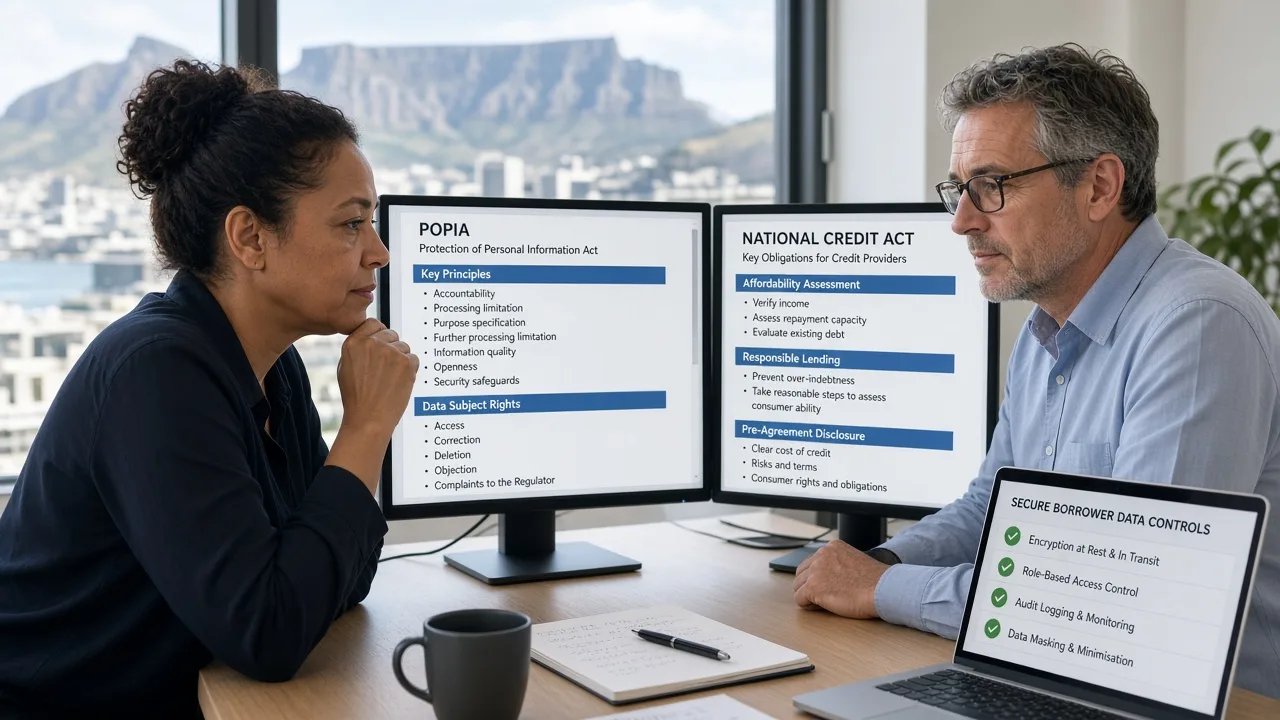
Protects borrower data with role-based access, encryption, secure login, and audit logs. A lending software development company can also build controls around POPIA requirements.
Cost: ZAR 10K–ZAR 40K
Major Factors That Shape Lending Software Development Pricing
Your budget depends on more than software features. Team location, developer experience, design work, licences, testing, and future growth also affect the final cost.
1. Development Team Location
Developer rates can vary across South Africa's major tech hubs. Here are indicative hourly rates by city for lending software development.
| South African city | Indicative hourly cost |
|---|---|
| Johannesburg | ZAR 450–1,300 |
| Cape Town | ZAR 500–1,400 |
| Pretoria | ZAR 400–1,100 |
| Durban | ZAR 350–1,000 |
| Stellenbosch | ZAR 450–1,200 |
2. Development Team Size and Experience
The team you hire affects both delivery time and budget. A junior freelancer may suit smaller tasks, while a complex lending platform may need senior developers, UI/UX designers, QA testers, and a project manager.
| Developer level | Typical hourly cost |
|---|---|
| Junior developer | ZAR 250–450 |
| Mid-level developer | ZAR 450–800 |
| Senior developer | ZAR 800–1,300 |
| Technical lead/architect | ZAR 1,000–1,800 |
| Freelance specialist | ZAR 400–1,500 |
| Team size | Typical setup | Monthly cost |
|---|---|---|
| Small team | 2–3 people | ZAR 80K–180K |
| Medium team | 4–6 people | ZAR 180K–400K |
| Large team | 7–10 people | ZAR 350K–700K |
3. UI/UX Design Requirements
A simple loan application screen needs less design work than a full borrower portal with admin dashboards and mobile layouts. Custom prototypes, user research, responsive design, and design revisions can increase the budget.
| Design scope | Includes | Estimated cost |
|---|---|---|
| Basic | Simple screens and standard layouts | ZAR 15K–35K |
| Standard | Custom UI, borrower portal, dashboard | ZAR 35K–80K |
| Advanced | User research, prototypes, complex workflows, web and mobile designs | ZAR 80K–180K |
4. Third-Party Software and Licensing
Lending platforms may use paid cloud services, SMS tools, identity verification APIs, reporting software, and security products. Licence fees and API usage charges can become recurring expenses as borrower numbers and transactions grow.
Cost: ZAR 0–25K+ per month, depending on tools, licences, and usage. Provider setup fees may apply separately.
5. Testing and Quality Assurance
QA testers check loan calculations, repayment schedules, payment records, API connections, and data security. Projects may also need performance testing, browser checks, user acceptance testing, and security reviews before launch.
Cost: ZAR 15K–80K+ for testing, depending on platform size and test coverage.
South African Regulations and Integrations That Influence Development Costs
Local laws and payment systems affect the features, security, and integrations your lending platform needs.
National Credit Act and NCR Requirements
The National Credit Act sets rules for credit providers in South Africa. Systems may need tools for affordability checks, credit records, and responsible lending. NCR registration duties depend on the lender and its activities.
POPIA and Customer Data Protection
POPIA requires lenders to protect personal data, such as ID numbers, bank details, and income records. Your platform may need data encryption, access controls, secure storage, and audit logs to protect borrower information.
FICA and Customer Due Diligence
FICA may require covered lenders to verify customer identities and check risks. Your system may need ID checks, document uploads, sanctions screening, and transaction records. These tools add work to the build.
DebiCheck and Local Payment Integrations
DebiCheck lets customers confirm debit order details with their banks. Connecting it with EFT and payment services helps lenders collect repayments and track failed payments. The required bank or provider setup affects development work.
Credit Bureau and Third-Party API Integrations
Credit bureau APIs help lenders check credit history and assess borrower risk. Other APIs can support ID checks, bank data, and payment services. Each connection needs setup, testing, and ongoing support.
When planning custom software development costs in South Africa, include these local integrations from the start. They can add time and cost to your lending platform.
Technology Stack Required to Build a Lending Platform
The right technology stack affects your platform’s speed, security, and long-term cost. Here are the main tools and their estimated cost levels.
| Technology layer | Common technology options | Cost level |
|---|---|---|
| Frontend development | React, Angular, Vue.js | Medium |
| Backend development | Node.js, Python, Java, .NET | Medium to High |
| Mobile app development | Flutter, React Native, Kotlin, Swift | Medium to High |
| Database | PostgreSQL, MySQL, MongoDB | Low to Medium |
| Cloud hosting | AWS, Microsoft Azure, Google Cloud | Medium to High |
| API development | REST APIs, GraphQL | Medium |
| Security and authentication | OAuth 2.0, JWT, multi-factor authentication | Medium to High |
| Payment integration | EFT, DebiCheck, payment gateway APIs | Medium to High |
| Testing and quality assurance | Selenium, Cypress, JUnit | Low to Medium |
| Reporting and analytics | Power BI, Metabase, custom dashboards | Medium |
Web-Based Lending Platform vs Mobile Lending App: Cost Comparison
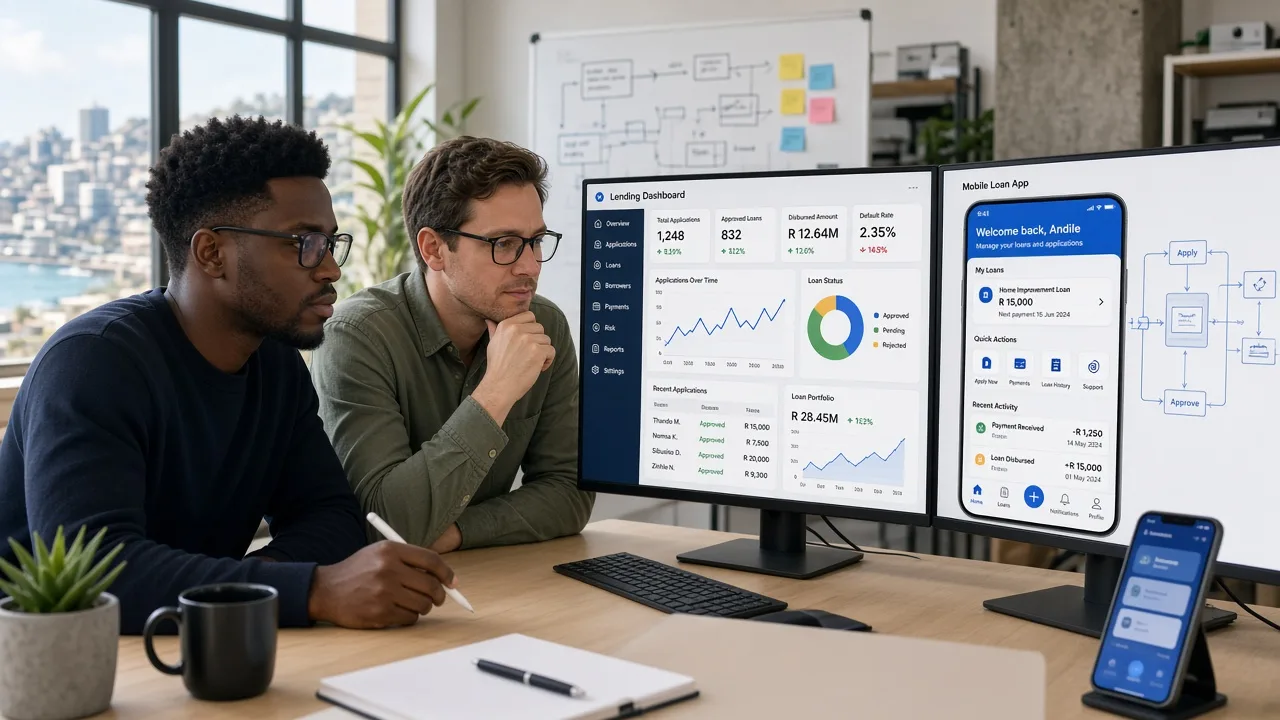
A web platform costs less to launch, while a mobile app adds development, testing, and maintenance costs.
| Cost factor | Web-Based Lending Platform | Mobile Lending App |
|---|---|---|
| Estimated development cost | ZAR 100K–400K | ZAR 150K–500K |
| Development time | Around 8–16 weeks | Around 10–20 weeks |
| User access | Through a web browser | Through a mobile app |
| User interface | Responsive website for desktop and mobile | App designed for iOS and Android |
| Main features | Loan applications, borrower dashboard, loan tracking, repayment management | Mobile loan applications, push alerts, document uploads, repayment tracking |
| Integrations | Payment gateways, credit bureaus, and third-party APIs | Payment APIs, device features, push notification services, and credit bureau APIs |
| Testing needs | Browser and device testing | Device, operating system, and app performance testing |
| Maintenance costs | Usually lower | Can be higher due to app updates and platform support |
| Best suited for | Lenders who want to launch a platform across devices | Lenders who want a mobile-first borrower experience |
Hidden and Ongoing Costs of Running Lending Software
Building your lending platform is only the first expense. Hosting, updates, security, and support also add to the long-term cost.
1. Cloud Hosting and Server Costs
Your lending platform needs servers to store data and handle loan activity. Cloud services like AWS and Microsoft Azure charge for storage, traffic, and computing power. Costs can rise as more borrowers use the system.
2. Software Updates and Maintenance
Regular updates fix bugs, improve performance, and keep your platform working with new devices and systems. You may also need changes to loan rules, reports, and payment features as your business grows.
3. Security and Data Protection
Lenders handle sensitive details like ID numbers, bank records, and income data. Regular security checks, data backups, access controls, and system monitoring help protect this information and support POPIA requirements.
4. Third-Party API and Integration Fees
Credit bureau checks, identity verification, payment gateways, and SMS services may charge setup or usage fees. These costs depend on the provider, number of checks, and volume of transactions your lending platform handles.
5. Technical Support and Monitoring
Your team may need ongoing help to fix errors, manage user access, check system performance, and solve payment issues. Support plans can also cover urgent problems that affect loan applications or repayments.
6. Mobile App Updates and Support
If your lending business has an app, you must support new Android and iOS versions, fix app errors, and release updates. These tasks add to the mobile app development cost in South Africa, especially when you maintain apps for both platforms.
7. Compliance and Legal Review
Lending rules and data protection duties can change. You may need legal advice, compliance reviews, updated customer agreements, and changes to system records or reports. The exact work depends on your lending activities and legal duties.
8. Staff Training and User Onboarding
Employees need training to use loan dashboards, approval tools, repayment records, and reports. You may also need user guides and onboarding support when new staff join or your lending process changes.
9. Data Backup and Disaster Recovery
A system failure or data loss can interrupt loan operations. Regular backups and recovery plans help restore borrower records, payment details, and loan histories. Storage and recovery tools may add to your monthly costs.
How to Reduce Lending Software Development Costs Without Compromising Quality
You can lower development costs by planning carefully, choosing essential features, and avoiding work that adds little value.
- Start With an MVP — Build a basic version with loan applications, borrower records, approvals, and repayment tracking. Add advanced features after you test the platform with real users.
- Set Clear Project Requirements — List your business goals, users, workflows, and must-have features before development. Clear requirements help prevent scope changes, delays, and extra costs.
- Choose the Right Technology Stack — Use reliable tools that fit your platform size and budget. Open-source frameworks and cloud services can reduce licence and setup costs.
- Use Ready-Made Tools Where Practical — Use trusted tools for email alerts, identity checks, reporting, and payment services. Custom-build only the features that support your main lending process.
- Plan Integrations Early — List the credit bureau, payment gateway, banking, and identity APIs you need. Early planning helps avoid costly changes during development.
- Build for Future Growth — Choose a flexible system that can handle more borrowers, loans, and transactions over time. A scalable design can reduce the need for a costly rebuild.
- Test During Development — Check loan calculations, payment records, security, and user access throughout the project. Early testing helps catch errors before they become expensive fixes.
- Work With the Right Development Partner — Choose a team with lending, finance, API, and data security experience. A trusted banking software development company can help plan the right features and avoid wasted development work.
- Avoid Unnecessary Custom Features — Do not add every feature at launch. Focus on tools that solve real business needs, then use customer feedback to guide future updates.
Common Mistakes That Increase Lending Software Development Costs
Small planning mistakes can lead to delays, extra work, and higher lending software development costs.
-
Adding Too Many Features at Launch
Mistake: Building every feature at once increases coding time, testing work, and the project budget.
Solution: Start with core loan features, such as applications, approvals, and repayment tracking. Add more later. -
Changing Requirements Midway
Mistake: Frequent changes to loan rules, dashboards, or workflows can cause delays and extra development costs.
Solution: Set clear project goals and approve the main features before development begins. -
Ignoring Local Regulations
Mistake: Missing POPIA, National Credit Act, or relevant NCR requirements can lead to costly system changes.
Solution: Review legal duties with a South African compliance expert before building the platform. -
Choosing the Wrong Technology
Mistake: Poor technology choices can cause slow performance, security gaps, and costly upgrades as your platform grows.
Solution: Pick a suitable tech stack that supports data security, API links, and future growth. -
Underestimating Third-Party Integrations
Mistake: Late planning for credit bureau, DebiCheck, and payment gateway APIs can add time and cost.
Solution: List required providers early. Check their fees, API access, setup needs, and testing steps. -
Skipping Testing and Quality Checks
Mistake: Poor testing can leave errors in loan calculations, payment records, user access, and security.
Solution: Test each feature during development. Run checks for loan workflows, data protection, and payment accuracy before launch.
How to Choose a Lending Software Development Company in South Africa
Choose a development partner with lending experience, strong security skills, and knowledge of South African regulations.
- Check Lending Experience: Look for experience with loan management systems, loan origination, credit scoring, and digital lending platforms.
- Review Past Projects: Ask for examples of fintech software, borrower portals, loan apps, and payment integration projects.
- Check Local Knowledge: Choose a team familiar with South African lending needs, the National Credit Act, NCR rules, and POPIA.
- Ask About Security: Check their approach to data encryption, secure logins, access controls, backups, and audit trails.
- Confirm API Experience: Make sure they can connect credit bureaus, DebiCheck, payment gateways, banking APIs, and identity checks.
- Discuss NDA Terms: Sign a Non-Disclosure Agreement (NDA) before sharing loan models, business plans, customer data, or other confidential details.
- Understand Project Costs: Request a clear quote covering development, testing, integrations, deployment, and ongoing maintenance.
- Check Communication: Choose a team that shares regular updates, explains technical issues clearly, and responds to questions.
- Review Support Plans: Ask about bug fixes, software updates, cloud monitoring, security patches, and post-launch support.
- Confirm Code Ownership: Make sure your contract explains who owns the source code, software rights, and project documentation.
- Ask About Scalability: Choose a team that can support more borrowers, loan products, transactions, and future integrations.
Explore our lending software development company in South Africa services to align scope, compliance, and budget before you sign.
Conclusion
The lending software development cost in South Africa depends on your platform type, features, integrations, and security needs.
A simple loan management system may fit a smaller budget, while a full digital lending platform needs more time and investment. Plan your budget for development, testing, cloud hosting, and ongoing support.
Most importantly, choose a skilled development partner who understands South African lending rules and payment systems. Start with what your business needs today, then build room for growth.
Frequently Asked Questions
1. How much does lending software development cost in South Africa?
Lending software development can cost between ZAR 40K and ZAR 1M, depending on features, platform type, integrations, and security needs.
2. How long does it take to build lending software?
A basic platform may take 4–8 weeks. A larger lending system with custom workflows and integrations can take 4–8 months.
3. What type of lending software can I build?
You can build loan origination software, loan management systems, digital lending platforms, P2P lending software, or mobile loan apps.
4. What features should a lending platform include?
Core features include loan applications, borrower management, credit scoring, loan approvals, repayment tracking, payment integration, and reporting.
5. Does lending software need to comply with POPIA and the National Credit Act?
Yes, applicable lenders must meet relevant legal duties. Software can support data protection and lending processes, but cannot guarantee compliance.
6. Can I integrate DebiCheck into lending software?
Yes. DebiCheck integration can help manage debit order authorisations and repayment collections through supported banks or payment providers.
7. How much does it cost to maintain lending software?
Maintenance costs vary by platform size and support needs. Budget for hosting, security updates, bug fixes, API fees, and technical support.
8. Can I start with a basic lending platform and add features later?
Yes. Start with an MVP that covers core loan operations. Add advanced features, integrations, and mobile apps as your business grows.