Ever watched a shopper leave a full cart because the total felt too big? It happens every day.
Buyers want the item now, but payday is far away. Stores lose the sale. Shoppers feel stuck. BNPL fills that gap.
So, is Buy Now Pay Later (BNPL) app development in South Africa worth your time? Yes, if you plan it well. It can lift sales and build loyal users.
In this blog, we cover how BNPL works, top providers, features, build steps, cost, rules, ecommerce integration, revenue, risks, and trends.
What Is BNPL and How Does It Work in South Africa?
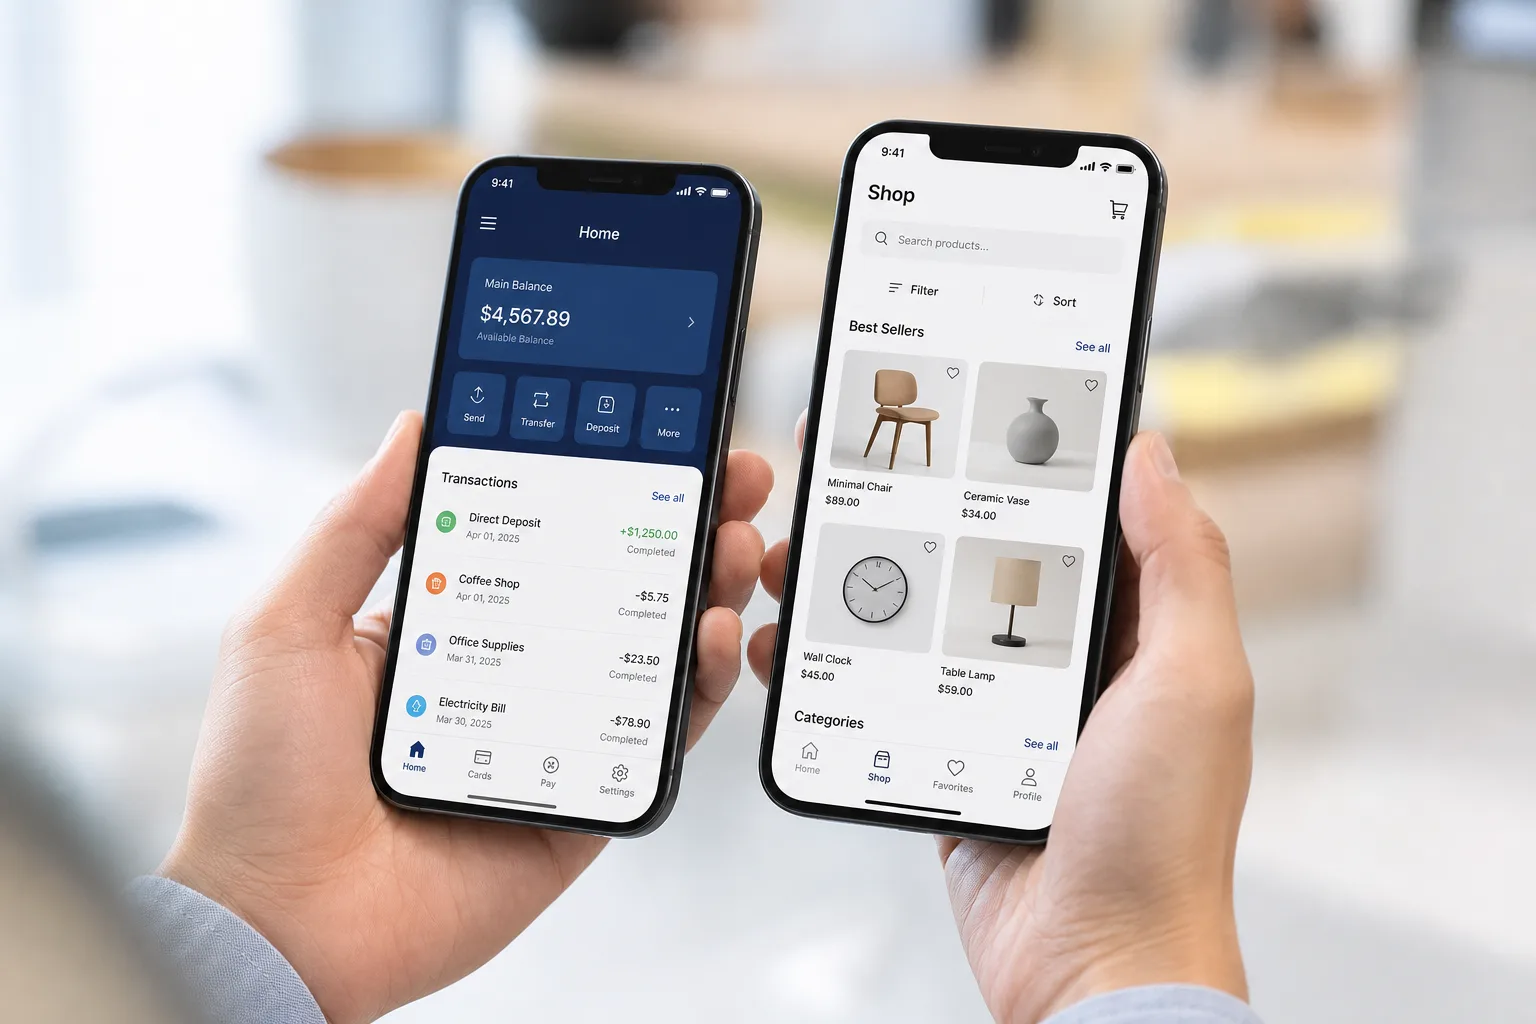
A BNPL app lets shoppers get an item today and pay for it in smaller instalments later. The app checks the buyer, pays the merchant, and collects each repayment on a set date.
Here is how it works in simple steps.
- The shopper picks BNPL at checkout and shares basic details.
- The app runs identity checks and an affordability check in seconds.
- If approved, the shopper pays a small first amount or nothing upfront.
- The merchant gets paid, and the BNPL provider takes on the repayment risk.
- The app collects the remaining instalments on the agreed dates and sends reminders.
Buy Now, Pay Later Apps: Key Market Statistics
Explore the BNPL app market size, growth trends, revenue forecasts, adoption rates, and key factors driving flexible digital payments worldwide.
- South Africa’s BNPL market is projected to grow from US$717.3 million in 2024 to US$1.30 billion by 2030, at a 9.8% CAGR, driven by e-commerce expansion and flexible payment adoption.
- South Africa’s BNPL market is projected to grow from US$164.5 million in 2026 to US$913.6 million by 2033, at a 27.8% CAGR, with online channels accounting for 85.39% of revenue in 2025.
- South Africa’s FinTech payments and BNPL market was valued at USD 2.5 billion, driven by digital payment adoption, e-commerce growth, and rising demand for flexible payment options.
Popular Buy Now, Pay Later Providers in South Africa
These local names already shape how South Africans pay in parts. Study them before you build.
These players do not all use the same credit model. Do not treat them as copies of each other. Always verify product details before you publish or plan around them.
| Provider | What to Know |
|---|---|
| Payflex | A popular instalment option used at many online stores. Known for simple checkout. |
| PayJustNo | Splits purchases into three payments over time at partner stores. |
| HappyPay | Built around customer pay cycles, so repayments can match when salaries land. |
| MoreTyme | BNPL inside a digital banking setup. Check current availability before comparing. |
| Float | A card-linked instalment product. Check its current model before you compare. |
| Mobicred | A credit account for online shopping with monthly repayments. Different from pay in 3. |
What Business Opportunities Can BNPL Apps Create in South Africa?
BNPL opens new income streams for startups, banks, and online stores. Here is where the best openings sit today.
Smart Buy Now Pay Later (BNPL) app development in South Africa starts with picking one clear path. Do not try all of them at once. I learned that the hard way on early projects.
Independent BNPL Fintech App
You can build your own BNPL brand from scratch. This path needs more money, but you own the data and the customer. Strong fintech app development skills in South Africa help here.
BNPL for Existing Stores
Already run an online shop? Add instalments at checkout. Shoppers see smaller payments and may spend more. You keep your brand and control the buying journey.
White Label BNPL Solutions
Build one platform and let retailers use it under their own name. You earn licence fees or a share of each sale. It scales fast once a few big merchants sign on.
Retail, Fashion and Electronics
Big ticket items fit BNPL well. Think phones, laptops, sneakers, and sofas. Buyers want to spread the cost, and stores want bigger baskets.
Merchant and Provider Partnerships
Stores need a lender. Lenders need stores. Connect them through APIs, and both sides win. Good partnerships also cut your customer acquisition cost.
Essential BNPL App Features for Secure Payments
Good BNPL apps feel simple for shoppers and safe for lenders. These five features matter most.
Instant Eligibility Decisions
Shoppers want an answer in seconds. Your app should run KYC, identity verification, and affordability checks fast. Use underwriting rules and credit data to approve or decline.
Clear spending limits build trust. In my view, a fast "no" is better than a slow "maybe".
Checkout Widget and Instalment Plans
A BNPL checkout widget shows pay in 3 or pay in 4 options right on the cart page. The buyer sees the repayment calendar before paying. Add a small down payment option for bigger baskets.
Clear numbers cut surprise and support calls.
Merchant Dashboard
Stores need a merchant dashboard to track orders, settlements, refunds, and payment reconciliation. Without it, support teams drown in spreadsheets.
Add simple reports on approval rate and average order value. Merchants love numbers they can act on.
Risk and Fraud Controls
Fraud scoring, transaction monitoring, and account takeover prevention protect both sides. Add default probability models to spot weak accounts early.
One mistake I see often is adding fraud tools after launch. Add them first. Fixing losses later costs far more.
Automated Repayments and Alerts
Automated repayment management pulls payments on due dates. Real time notifications and payment reminders cut missed payments. Add retry rules for failed payments and a simple collections flow.
Step-by-Step Guide to BNPL App Development
Follow these nine steps to move from idea to launch without costly detours. Each one builds on the last.
Every project of Buy Now Pay Later (BNPL) app development in South Africa follows a path like this. Skip a step and you will pay for it later.
Step 1. Research the Market and Validate Your Business Idea
Look at the South African BNPL market. Study shopper habits, local competitors, and gaps in service. Talk to real merchants and buyers.
Ask one question. Will people pay for this, and will stores adopt it?
Step 2. Choose Your BNPL Business Model
Pick one model to start.
- Merchant-funded BNPL: Stores pay a small fee on every sale, and shoppers pay no extra cost.
- White label payment platform: You build the system once, and retailers use it under their own brand name.
- Embedded lending inside an e-commerce app: Shoppers get instalment options inside the store app, so they never leave the checkout.
Step 3. Define Your Target Customers and Merchant Partners
Decide who you serve first. Maybe it is young shoppers buying fashion. Maybe it is families buying electronics.
Then find five to ten merchants who will test your app early.
Step 4. Plan the App Features and User Experience
Start with a simple list of must-have features. Then cut that list in half for your MVP. A small first version is easier to test, fix, and launch.
Next, map the full customer journey. Draw wireframes for each key screen before any code gets written.
- Onboarding: Keep sign-up short. Ask for only what you need for KYC and identity verification.
- Eligibility result: Show the spending limit in seconds, with a clear reason if the answer is no.
- Checkout: Place the BNPL checkout widget on the cart page, with the pay in 3 or pay in 4 choice.
- Repayment calendar: Show every due date and amount before the shopper agrees.
- Customer account: Add transaction history, payment reminders, and an easy way to pay early.
Step 5. Select Your Technology Stack and Payment Integrations
Your stack shapes speed, cost, and security. Here is a sample setup to discuss with your team.
These are tools to investigate. Check current API access, fees, and terms before you commit.
| Layer | Options to Consider |
|---|---|
| Mobile app | Flutter, React Native |
| Backend | REST APIs, microservices, PostgreSQL |
| Cloud | Amazon Web Services, Microsoft Azure |
| Payments | PayFast, Peach Payments, Stitch |
| Ecommerce | Shopify, WooCommerce, Adobe Commerce |
| Security | Database encryption, audit logs, API authentication |
Step 6. Develop the Customer App, Merchant Portal, and Admin Dashboard
A BNPL platform is not one app. It is three connected parts that share one backend. Build them in the right order, and each part gets easier.
Start with the customer app. Then add the merchant portal. Finish with the admin dashboard.
- Customer app: Handles sign-up, KYC, spending limit, instalment schedule, and payment reminders. Shoppers also see their transaction history here.
- Merchant portal: Lets stores track orders, settlements, refunds, and payment reconciliation. It also holds API keys and plugin setup for Shopify and WooCommerce.
- Admin dashboard: Gives your team control over credit risk rules, fraud scoring, collections, and audit logs. Reports on approval rate and repayment collection rate live here too.
Connect all three through REST APIs and webhooks. When a shopper pays, the merchant portal and admin dashboard should update at once. Delays here create angry support calls.
Set up a sandbox environment before you touch real money. Use test accounts, fake cards, and dummy orders. Try failed payments, refunds, and cancelled orders too.
Step 7. Integrate Risk Assessment, Fraud Prevention, and Repayment Systems
This step decides if your business survives. Do not rush it.
- Credit risk assessment: Connect credit data and affordability checks. Set approval limits and keep them small for new users.
- Fraud prevention: Add KYC, fraud scoring, and transaction monitoring to catch fake accounts early.
- Repayment and collections: Automate due date payments, send reminders, and retry failed payments before they become defaults.
Test every rule with real cases. I have seen one weak limit rule cause big losses in a single month.
Step 8. Test Security, Payment Flows, and App Performance
Test every path before real shoppers touch your app. One missed bug in a payment flow can cost real money.
- Payment flow testing: Check authorisation, instalment schedules, failed payments, refunds, and cancelled orders. Each one should update the repayment calendar correctly.
- Security testing: Run penetration tests, check API authentication, and confirm database encryption. Review audit logs and POPIA data safeguards too.
- Performance testing: Run load tests for sale days like Black Friday. Checkout should stay fast when traffic jumps.
Use automated testing and CI/CD pipelines to catch bugs early. Every new update then gets checked before it goes live.
Step 9. Launch, Monitor Performance, and Scale the Platform
Do not launch to everyone on day one. Start with a small group of shoppers and a few trusted merchants.
Then watch the numbers closely.
- Approval rate: Shows if your eligibility rules are too strict or too loose.
- Repayment collection rate: Tells you how many instalments get paid on time.
- Uptime and speed: Real-time monitoring helps you fix outages before merchants notice.
- Default and fraud alerts: Catch weak accounts and suspicious transactions early.
Fix problems fast, then add merchants slowly. Growth without control leads to default losses.
Once your numbers stay steady, scale with more plugins, more retail partners, and better risk models. Slow and steady wins here.
How Much Does BNPL App Development Cost in South Africa?
Your fintech app development cost in South Africa depends on scope, risk tools, and compliance. Plan early.
Typical budgets run from ZAR 150K to ZAR 1.2M+. The table below shows basic to enterprise levels.
| Level | What You Get | Estimated Cost | Timeline |
|---|---|---|---|
| Basic MVP | Customer app, simple checkout, basic repayments | ZAR 150K to ZAR 350K | 2 to 3 months |
| Standard | Merchant dashboard, risk rules, notifications | ZAR 350K to ZAR 700K | 4 to 6 months |
| Advanced | Fraud scoring, plugins, reporting, scalability | ZAR 700K to ZAR 1.2M | 6 to 9 months |
| Enterprise | White label platform, full compliance tools, custom integrations | ZAR 1.2M+ | 9 to 12 months or more |
What Regulations Must BNPL Apps Follow in South Africa?
Always check the rules before you build Buy Now Pay Later (BNPL) app development in South Africa into a real product. The right rules depend on your product and the parties involved.
This is not legal advice. Have a qualified South African lawyer review your plan.
National Credit Act and National Credit Regulator
The National Credit Act covers consumer credit and credit provider registration. The National Credit Regulator oversees registration and compliance.
Not every BNPL app needs the same registration. Your model decides.
Consumer Protection and Clear Payment Terms
Show the full cost, due dates, and late fees before the shopper agrees. Use plain words. Avoid hidden charges.
Responsible lending is also good business. Trusting customers repay more.
Payment Processing, Fraud Prevention, and Security
Payments run inside the national payment system, which the South African Reserve Bank oversees. The Payments Association of South Africa offers industry context.
The FSCA may also matter, depending on your activities.
POPIA and Personal Information
You will hold IDs, phone numbers, and payment data. The Protection of Personal Information Act sets rules for safe handling. Collect only what you need. Ask for consent. Encrypt everything.
Credit Reporting and Emerging BNPL Rules
BNPL rules are still changing. Credit reporting may become more common as the market grows.
Follow regulator updates. Build your app so you can add reporting later.
How Can BNPL Integrate With Ecommerce Platforms in South Africa?
Integration is where BNPL meets real shoppers. Done well, it feels like part of the store.
- BNPL integration with Shopify and WooCommerce uses plugins, APIs, and webhooks for fast setup.
- Custom e-commerce website and app integration works best with trusted mobile app development services in South Africa.
- Adding BNPL to checkout means a widget, an authorisation call, and a clear repayment preview.
- Merchant onboarding and settlement workflows need quick setup, clear payout dates, and easy reconciliation.
- Refunds, failed payments, and order cancellations must update the instalment schedule automatically.
- Smaller visible payments can lift checkout conversion and average order value and cut cart abandonment.
BNPL Revenue Models and How BNPL Apps Make Money
BNPL apps earn in a few steady ways. Know them before you set your pricing.
- Merchant discount rate: a small fee the store pays on each BNPL sale.
- Late fees, where the law allows, charged when customers miss due dates.
- Interest on longer plans, for products that go beyond short instalments.
- Platform licensing, when retailers pay to use your white label payment platform.
- Transaction commissions from partners, such as payment gateways and ecommerce platforms.
- Lower customer acquisition cost and fewer default losses through better risk scoring.
What Challenges Can Businesses Face When Building a BNPL App?
Every BNPL project hits bumps. Knowing them early saves money and stress.
Customer Defaults and Repayment Risk
The challenge. Some buyers miss payments, and unpaid balances hurt your cash flow fast.
The fix. Use affordability checks, small starting limits, and automatic reminders before due dates.
Fraudulent Transactions and Identity Theft
The challenge. Fake accounts and stolen details can drain funds before you notice the problem.
The fix. Add KYC, fraud scoring, and live transaction monitoring from day one of your launch.
Regulatory Uncertainty and Compliance Costs
The challenge. Rules shift, and compliance can push your custom software development cost in South Africa higher.
The fix. Get legal advice early and build flexible systems so new rules need small changes only.
Merchant Adoption and Customer Acquisition
The challenge. Stores hesitate to add a new payment option, and shoppers need a reason to switch.
The fix. Offer easy plugins, a pilot with a few merchants, and clear proof of better checkout results.
Competition From Established BNPL Providers
The challenge. Local players already have brand trust, merchant deals, and loyal users.
The fix. Pick a niche, like a certain retail type, and serve it better than the big names do.
Building Consumer Trust and Responsible Lending
The challenge. Shoppers fear hidden fees and debt traps, so trust is hard to win.
The fix. Show every cost upfront, set fair limits, and treat support questions like real conversations.
Future of BNPL in South Africa and Trends to Watch
The market is still young, which means room to grow. These trends are worth watching.
- More e-commerce stores are adding BNPL as shoppers expect flexible payment options.
- Banks and digital banks are building BNPL into their own apps through embedded finance.
- Advances in mobile app development in South Africa are helping businesses build smoother BNPL experiences, with faster onboarding, secure payments, and real-time repayment updates.
- Smarter credit risk assessment using live data and machine learning.
- Stronger regulation and more attention to responsible lending and credit reporting.
- Growth in online to offline commerce, with BNPL used in physical stores.
- Faster merchant onboarding through simple APIs and mobile SDKs.
- Better fraud detection to protect users as digital payments in South Africa keep growing.
Conclusion. Is Building a BNPL App in South Africa Worth It?
Yes, it can be if you build with care. Buy Now Pay Later (BNPL) app development in South Africa offers real room for startups, banks, and online stores.
Success depends on three things. Strong risk control, clear compliance, and a smooth checkout. Start with an MVP, test with real merchants, and grow step by step.
Get legal advice early and plan your budget honestly. Do that, and your BNPL app can turn abandoned carts into happy customers.
Frequently Asked Questions
How much does it cost to develop a BNPL app in South Africa?
BNPL app development can cost ZAR 150,000 to ZAR 1.2 million or more, depending on features, integrations, security, and compliance needs.
How long does it take to build a BNPL app?
A basic BNPL app may take 2–3 months. A complex platform with merchant tools, risk controls, and custom integrations can take 6–12 months or longer.
Do BNPL apps need NCR registration in South Africa?
Some BNPL models may require registration under the National Credit Act. The answer depends on the product structure, so seek legal advice before launch.
How do BNPL apps make money?
BNPL apps can earn through merchant transaction fees, platform licensing, and permitted charges. Profit depends on repayment rates, operating costs, and fraud losses.
Can I add BNPL to my Shopify or WooCommerce store?
Yes. BNPL can be added through a supported plugin or API integration. Check provider compatibility, fees, and settlement terms before choosing a solution.
What features should a BNPL app include?
Key features include customer verification, eligibility checks, instalment schedules, secure payments, repayment reminders, fraud controls, and a merchant dashboard.
Is BNPL app development profitable in South Africa?
It can be profitable if merchants adopt the service and customers repay on time. Strong risk controls, fair fees, and low operating costs matter.
What technology is best for building a BNPL app?
Flutter or React Native can support mobile apps, while a secure backend, database, payment APIs, and cloud hosting handle transactions and repayments.